


Shareholders and investors need to understand financial concepts about listed companies. One that really interests them is the “payout”: the share of profits that a company “pays out” to them. Below is everything you need to know about payouts.
A payout is the share of profits that a listed company will pay its shareholders. If the payout set out in the company’s shareholder remuneration policy is 50%, the company will distribute half of its net profits among its shareholders.
If that policy says the 50% payout should be split between a cash dividend and share buybacks, the formula is:
Payout = (cash dividend + share buyback)/underlying net profit. The payout is expressed as a percentage.
Remember, a dividend is cash paid to shareholders for their share in the company's profits. A share buyback and the subsequent cancellation of shares are when the company “buys back” its own shares to reduce outstanding share capital and increase its share price.
Why do payouts matter to shareholders?
The payout is an indicator that influences an investor’s decision to buy shares in a company. It shows what share of the company’s profits will be paid to shareholders, whether in a cash dividend, a share buyback or both.
What does this mean?
A payout policy can also help attract more long-term investment in a listed company. But the company must find the right balance between shareholder returns and reinvesting in its own long-term growth. A payout gives substance to shareholder remuneration policies, which influence investors’ decisions.
Shareholder remuneration
In application of the current shareholder remuneration policy charged against 2026 results:
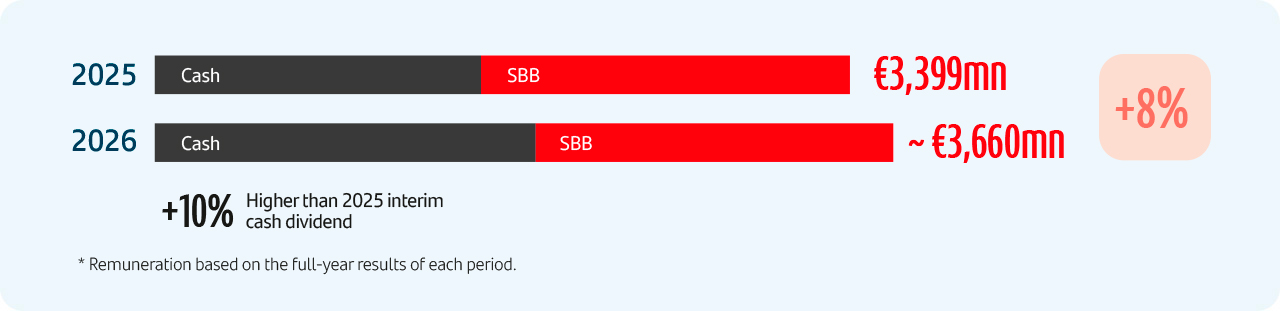
- On 29 September 2026, the board of directors approved an interim cash dividend of EUR 12.70 cents per share, 10% higher than its 2025 equivalent, which was paid in November. Including the EUR 12.50 cent cash dividend per share paid in May, the cash dividends per share paid during 2026 will be 12% higher than that paid in 2025.
- On 10 August 2026, we announced the first 2026 buyback programme of up to EUR 1,825 million, which has been completed.
This programme puts us on track to achieve our goal of distributing at least EUR 10 billion through share buybacks charged against 2025 and 2026 results and against expected capital excess1. Considering this new programme, we will have carried out approximately 90% of this goal.
Total shareholder remuneration charged against H1 2026 results will be approximately EUR 3,660 million, 8% higher than the remuneration charged against H1 2025 results. The amount is approximately 50% of H1 2026 underlying attributable profit, split broadly equally between cash dividend payments and share buybacks.
At the end of the quarter, TNAV per share was EUR 5.92. Including the final cash dividend charged against 2025 results and the interim dividend charged against 2026 results approved in September, TNAV per share increased 11% year-on-year.
1 As previously announced, Santander intends to allocate at least EUR 10 billion to shareholders through share buybacks charged against 2025 and 2026 results and against the expected capital excess. This share buyback target includes: i) buybacks that are part of the existing shareholder remuneration policy; and ii) additional buybacks following the publication of annual results to distribute year-end excesses of CET1 capital. The implementation of the shareholder remuneration policy and additional buybacks is subject to corporate and regulatory decisions and approvals.